Report Summary
Period covered 02 August – 29 August 2026
3 minute read
Note: This report summary is one or two months behind the current month as standard reporting practice. The content is indicative only and incomplete with certain data undisclosed. Become a member to access this data or take out a free 30-day membership trial now.
DIY & Gardening Sales
DIY and gardening sales increased by xx% year-on-year in August, comfortably ahead of the xx% rise recorded in the same month last year. Growth also strengthened from xx% in July, reversing some of the slowdown that followed stronger increases earlier in the summer.
August was the UK's joint sixth-warmest August on record and brought the warmest UK summer since records began, keeping gardens and outdoor living relevant well beyond the early summer period.
But the nature of the weather was becoming less uniformly helpful, with persistent dry conditions presenting a more difficult environment for parts of the sector.
Key trading themes and drivers
Warm weather remained an important influence during August, with another heatwave arriving in the middle of the month after similar conditions earlier in the summer. The longevity of the warm weather gave households an extended period in which gardens and outdoor spaces could be used, helping to keep the category relevant.
The exceptionally dry conditions did create a more difficult month for some areas of gardening. HTA garden centre data showed gardening sales among its members fell YoY, including declines in bedding plants, hardy plants and plant care. Perhaps this is not as surprising given the ongoing hosepipe ban in parts of the UK.
The economic environment also became less favourable as the month progressed. Inflation increased to xx%, wage growth slowed and households were told that energy bills would rise again in October. DIY and gardening still managed to rise against this background, leaving the category ahead of its performance last August despite growing pressure on discretionary incomes.
Macroeconomic backdrop
The overall financial position facing households became more difficult during August as CPI inflation stepped up, while regular wage growth slowed to xx%, leaving earnings only narrowly ahead of inflation.
Household energy costs will add another pressure during the autumn. Electricity, gas and other household fuels were already xx% more expensive than a year earlier, with Ofgem confirming a further xx increase in the energy price cap from 1 October, taking the annual bill for a typical dual-fuel household to £1,723. Higher essential expenditure will make larger or less urgent home projects easier to postpone.
Housing activity also remains weak, with mortgage approvals falling to xx in July, around xx below a year earlier and their lowest level since January 2024, while the effective interest rate on newly drawn mortgages increased to xx.
The Bank of England subsequently held Bank Rate at xx% in September, although three members of the MPC committee voted to raise rates to xx%. Fewer house moves remove one of the occasions that can generate decorating, repair and renovation spending, while expensive borrowing leaves existing homeowners facing higher costs.
Conditions in the labour market provide another reason for caution, with payrolled employment estimated to have fallen by xx in August and vacancies dropping to xx, their lowest level since 2021.
Consumer confidence was a bright spot, improving to its highest level in two years, but the narrowing gap between wages and inflation, higher energy bills and weaker employment conditions mean households still face competing demands on their finances.
Take out a FREE 30 day membership trial to read the full report.
UK growth has held up
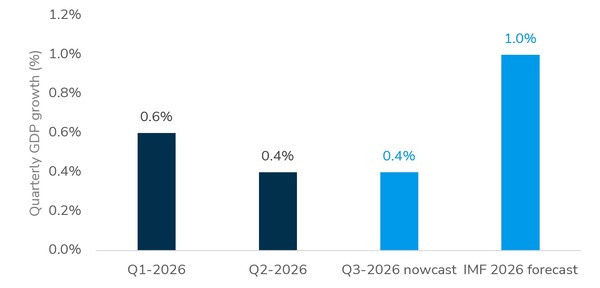 Source: Retail Economics analysis , ONS