UK Retail Inflation Report summary
September 2026
Period covered: Period covered: august 2026
3 minute read
Note: This report summary is one or two months behind the current month as standard reporting practice. The content is indicative only and incomplete with certain data undisclosed. Subscribe to access this data or take out a free 30-day subscription trial now.
Inflation
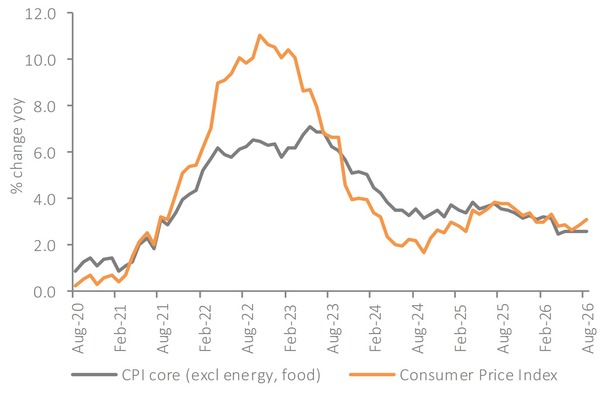
Headline inflation moves higher: CPI rose to xx% YoY in August, from xx% in July, in line with expectations.
The increase was concentrated in energy-related costs, with transport making the largest contribution to the monthly change.
Core inflation unchanged again: Core inflation has now held at xx% for four consecutive months, while services inflation remained at xx%. Goods inflation rose, but much of that increase came from energy-sensitive areas. There is still little evidence of a broader acceleration in domestically generated inflation.
Energy costs lift the headline rate: Fuel and household energy were the main sources of upward pressure in August. Motor fuel inflation rose to xx% YoY, while energy-related housing costs also increased.
Food remains soft: Food inflation stayed at xx% YoY, close to its lowest level since 2021. This is providing some offset to the renewed pressure from fuel and energy costs. The risk has not receded, with higher transport, energy and production costs still moving through supply chains.
Pay growth remains ahead of inflation, but gap narrows: Regular earnings grew by xx% YoY in the three months to July, meaning real pay growth remains positive, but the margin has narrowed as inflation has moved higher. This has reduced some of the improvement in household purchasing power seen earlier in the year and could leave consumers more sensitive to further increases in fuel and energy costs.
Producer cost pressure rises again: Producer price data moved higher in August, with output inflation rising to xx% YoY and input inflation to xx%. Commodity prices have also risen sharply since then. This increases the pressure on manufacturers and raises the likelihood of further cost pass-through over the coming months.
The latest rise in energy rises has yet to feed fully into CPI: Brent crude has risen to xxper barrel, up xx% MoM, while broader commodity indices have also moved sharply higher. August inflation therefore captures only part of the latest rise in energy costs. September’s release is likely to show more of that pressure, particularly through petrol and diesel.
Interest rate pressure remains limited for now: Markets still expect the Bank of England to hold rates at its next meeting, with an 80% probability of no change.
Inflation outlook: Headline inflation moved above xx in August, and September is expected to move higher again. Fuel is the main reason, with petrol and diesel rising sharply in August, and weekly pricing points to another increase in September.
The winter outlook now depends heavily on how long energy prices stay elevated. If current oil and gas prices persist, inflation could move above forecasts over the winter. Food inflation remains low, services inflation has not accelerated, and the parts of the basket most exposed to energy costs have yet to show a broad rise.
That gives the Bank of England some room to wait to make any adjustment to Bank Rate. The case for a rate increase would strengthen if elevated energy prices persisted long enough to push inflation forecasts materially higher
Take out a free 30-day trial subscription to read the full report >
CPI rose to 3.1% YoY in August, from 2.9% in July, in line with expectations.
 Source: ONS, Retail Economics analysis