UK Online Retail Sales Report summary
September 2026
Period covered: Period covered 02 August – 29 August 2026
3 minute read
Note: This report summary is one or two months behind the current month as standard reporting practice. The content is indicative only and incomplete with certain data undisclosed. Become a member to access this data or take out a free 30 day membership trial now.
Online performance
Online retail sales increased by xx% year-on-year in August, considerably ahead of the xx% rise recorded a year earlier and accelerating from July's xx% growth.
Household goods accelerated sharply, non-store retailers again grew considerably faster than their multichannel counterparts, but clothing and footwear slipped into decline for the first time since May 2025.
Key drivers
August's online performance came after several months in which exceptionally warm weather had influenced consumers shopping behaviours.
Another heatwave arrived during the month, with temperatures reaching 38.1°C at Kew Gardens and a new August record of 35.3°C in Wales, temporarily making trips to exposed shopping destinations less appealing. High street footfall fell particularly sharply during the hottest period, giving online an advantage when consumers wanted to avoid unnecessary journeys.
With less unmet seasonal demand to draw upon, online clothing and footwear sales declined xx% after several months of summer wardrobe spending.
Back-to-school provided a different source of demand during the second half of August as the mid month heatwave passed and attention began to turn towards September. The timing favoured categories associated with the return to school and work, but it did little to revive online fashion overall.
UK outlook: Better than feared, but far from comfortable
The UK economy has held up better than expected this year. Growth has been stronger than feared, retail volumes are still rising, and households entered the second half of 2026 in a better financial position than many expected at the start of the year.
The outlook becomes more difficult over the next few months as inflation rises again, borrowing costs remain elevated and higher energy and input costs work their way back through the supply chain.
Inflation is back at the centre of the outlook
The bigger concern is inflation, with CPI rising to xx% in August, its sharpest rise since March. We are now forecasting inflation to reach xx% in the fourth quarter, before moving above xx% in early 2027.
This is important as the improvement in spending power seen earlier this year relied partly on wages continuing to run ahead of inflation. As the gap closes, households will have less additional income to spend.
Interest rates also look less helpful, with Bank Rate remaining at xx%, but three MPC members voted for an immediate increase to xx% at their recent meeting in September. Markets are currently pricing in one quarter-point increase in Bank Rate before the end of the year.
For households refinancing mortgages or carrying other debt, borrowing costs could therefore stay restrictive for longer than previously expected.
Take out a FREE 30 day membership trial to read the full report.
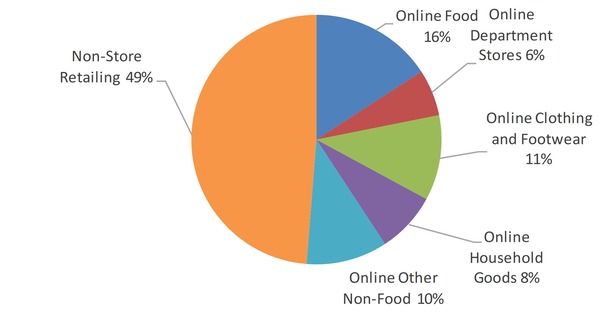
Proportion of online retail sales by category (Period aligned to ONS trading calendar 2 -29 August 2026)
 Source: ONS, Retail Economics analysis