UK Health & Beauty Sector Report summary
September 2026
Period covered: Period covered 02 August – 29 August 2026
3 minute read
Note: This report summary is one or two months behind the current month as standard reporting practice. The content is indicative only and incomplete with certain data undisclosed. Become a member to access this data or take out a free 30 day membership trial now.
Health & Beauty - Retail Economics Sales Index
Health and beauty was again the strongest performing retail sector in August, with sales increasing by xx% year-on-year, ahead of the xx growth recorded in the same month last year.
Growth eased from xx% in July and xx% in June, but the category retained a sizeable lead over the wider retail market, where sales increased by xx%.
The sector has grown consistently through the summer, maintaining strong growth as the performance of several other discretionary categories has weakened.
August's figures are particularly notable because they follow several months of elevated sales, leaving health and beauty one of the few areas where consumers were still spending substantially more than a year earlier.
Key trading themes and drivers
Seasonal demand extends: Another period of exceptionally hot weather provided favourable conditions for parts of the category during August, with temperatures reaching 38.1°C at Kew Gardens during the mid-month heatwave.
After similarly warm conditions earlier in the summer, products connected with sun protection and summer personal care remained relevant for longer than they would during a typical year. The persistence of the heat helped health and beauty retain some of the seasonal support that had contributed to its strong performance in June and July.
Summer boost eases: Consumers had already had several months to purchase products associated with hot weather, reducing the scope for the latest heatwave to generate the same incremental spending seen earlier in the season.
Affordable purchases support resilience: Health and beauty also benefited from the nature of the purchases made within the category. Much of the sector operates at lower individual price points than furniture, electricals or other larger discretionary purchases, and many products require regular replenishment. This gives spending a degree of resilience when household budgets are under greater pressure, particularly when compared with purchases that can be postponed for several months.
Household budget tightens: The wider economic picture became less favourable during August, with CPI inflation rising to xx% and regular wage growth slowing to xx. Yet health and beauty continued to grow at more than twice the rate of total retail, showing that consumers were still allocating money to the category despite tighter budgets.
Consumer behaviour
Everyday personal care provides recurring demand, whereas beauty, fragrance and other discretionary products give consumers scope to spend beyond essentials without necessarily taking on the financial commitment associated with larger ticket retail categories.
August's performance is particularly marked when compared with clothing and footwear. Clothing growth slowed to xx%, and footwear sales declined xx%, yet health and beauty maintained growth of 5.7%. After several months of unusually warm weather, consumers had already made many of their summer wardrobe purchases, whereas personal care products required replenishment throughout the period.
Take out a FREE 30 day membership trial to read the full report.
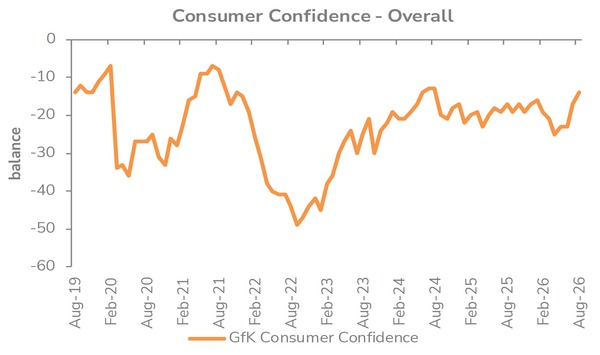
Confidence builds momentum
 Source: Retail Economics, GFK